What Happens If You Drive Without Insurance: Penalties, Risks, and What to Do Next
The Scope of Uninsured Driving in America
According to the Insurance Research Council, roughly one in eight drivers on American roads has no car insurance at all. That number translates to about 29 million uninsured motorists, and it has remained stubbornly consistent over the past decade despite state level efforts to crack down on the problem. Some states have uninsured rates above 20 percent, while others sit closer to 5 percent. The reasons people drive without insurance range from affordability issues to simple procrastination, but regardless of the reason, the consequences of getting caught are severe and often create a financial hole that is much deeper than the cost of the insurance itself.
State by State Penalties for Driving Uninsured
Every state except New Hampshire and Virginia requires drivers to carry minimum liability insurance, and even those two states have alternative financial responsibility requirements. The penalties for violating these laws vary widely, but they generally fall into several categories: fines, license and registration suspension, vehicle impoundment, and in some cases, jail time for repeat offenders.
First offense fines range from $100 in some states to over $1,000 in others. California charges between $100 and $200 for a first offense, but adds a $500 penalty if the violation is discovered during an accident. Florida does not fine you directly but suspends your license and registration for up to three years and requires you to pay a reinstatement fee of $150 to $500 depending on the number of offenses. New Jersey has some of the harshest penalties in the country: a $300 fine, community service, and license suspension for a first offense, plus a surcharge of $250 per year for three years. States like Michigan and Kentucky can impose fines above $500 for a first offense and significantly more for subsequent violations.
License Suspension and the Spiral It Creates
In most states, getting caught without insurance leads to an automatic suspension of your driver license, your vehicle registration, or both. This is where the real trouble begins for most people, because a suspended license does not eliminate the need to drive. People still have to get to work, pick up their children, and handle daily responsibilities. Many end up driving on a suspended license, which is a separate and more serious offense that can result in criminal charges, additional fines, and even arrest.
Reinstating a suspended license is not as simple as buying an insurance policy. Most states require you to file an SR-22, which is a certificate of financial responsibility that your insurer files with the state on your behalf. An SR-22 requirement typically lasts for three years, and during that time you will pay significantly higher insurance premiums because insurers view SR-22 drivers as high risk. The average SR-22 insurance policy costs 40 to 70 percent more than a standard policy. If you let your SR-22 policy lapse for any reason during the required period, your insurer notifies the state and your license gets suspended again. It becomes a cycle that is difficult and expensive to break.
What Happens If You Cause an Accident Without Insurance
The penalties for driving without insurance get much worse if you are involved in an accident while uninsured. In this situation, you are personally liable for all damages and injuries you cause. That means the other driver, their passengers, and their insurance company can all come after you for medical bills, vehicle repairs, lost wages, and pain and suffering. A moderate injury accident can easily produce $50,000 to $100,000 in claims, and a serious accident involving hospitalization, surgery, or long term disability can generate claims in the hundreds of thousands or even millions of dollars.
If you cannot pay these claims, the injured parties can obtain a court judgment against you. A judgment allows them to garnish your wages, seize assets, place liens on your property, and intercept tax refunds in many states. These judgments can follow you for 10 to 20 years depending on the state, and they can be renewed if the full amount has not been collected. Filing for bankruptcy may discharge some of these debts, but it will destroy your credit and make it extremely difficult to rent an apartment, get a loan, or sometimes even find employment for years afterward.
How States Are Catching Uninsured Drivers
States have gotten much better at identifying uninsured drivers in recent years. Many states now use electronic insurance verification systems that cross reference vehicle registration databases with insurance company records in real time. If your insurer reports that your policy has been canceled or has lapsed, the state's system flags your registration automatically and sends you a notice. If you do not provide proof of new coverage within a set period, your registration is suspended without you ever being pulled over by police.
License plate reader technology has also made it easier for law enforcement to identify uninsured vehicles on the road. Police cruisers equipped with automated plate readers can scan hundreds of plates per hour and instantly check each one against insurance databases. If your plate comes back as uninsured, the officer has probable cause to pull you over. Some cities have even mounted plate readers on traffic cameras and parking enforcement vehicles, meaning your car can be flagged as uninsured even while it is parked on a public street.
Affordable Alternatives If You Cannot Afford Standard Insurance
If cost is the reason you are driving without insurance, there are several options worth exploring before you take the risk of going uninsured. Many states offer low cost auto insurance programs specifically designed for low income drivers. California's Low Cost Auto Insurance Program provides liability coverage for as little as $250 per year for drivers who meet income eligibility requirements. New Jersey has a similar program called the Special Automobile Insurance Policy that offers basic coverage at reduced rates.
Pay per mile insurance is another option that can dramatically reduce costs for people who do not drive much. Companies offering this type of coverage charge a low base rate plus a per mile fee, typically between 3 and 7 cents per mile. If you drive less than 5,000 miles per year, pay per mile coverage can cost 30 to 50 percent less than a traditional policy. Usage based insurance programs that track your driving habits through a smartphone app or plug in device can also lead to significant discounts if you are a safe driver who avoids hard braking, speeding, and late night driving.
If you own your car outright and it is not worth much, you may be able to save money by dropping comprehensive and collision coverage and carrying only liability. Liability only policies cost significantly less than full coverage, and if your car is worth less than $4,000, the cost of carrying collision coverage often exceeds the potential payout in a total loss situation. Just make sure you carry enough liability coverage to protect your personal assets, because the minimum coverage required by your state is almost never enough to cover a serious accident.
Steps to Take If Your Insurance Has Already Lapsed
If you are currently driving without insurance because your policy lapsed, the most important thing you can do is get coverage as soon as possible. Every day you drive uninsured is a day you are exposed to potentially devastating financial consequences. Start by getting online quotes from several insurers, because rates for drivers with a coverage gap vary significantly from one company to another. Some insurers specialize in non standard or high risk drivers and may offer better rates than mainstream companies for someone with a lapse in coverage.
Be honest about your coverage gap when applying for a new policy. Insurers will verify your insurance history through industry databases, and lying on your application is grounds for policy cancellation or claim denial later. If your state has already flagged your registration due to the lapse, contact your department of motor vehicles after purchasing your new policy to find out what you need to do to reinstate your registration. In most cases, you will need to provide proof of your new insurance and pay a reinstatement fee. If an SR-22 is required, make sure your new insurer is able to file one in your state, because not all companies offer SR-22 filings.
Business Process Automation
Streamline operations and cut costs with intelligent business process automation solutions.
Read More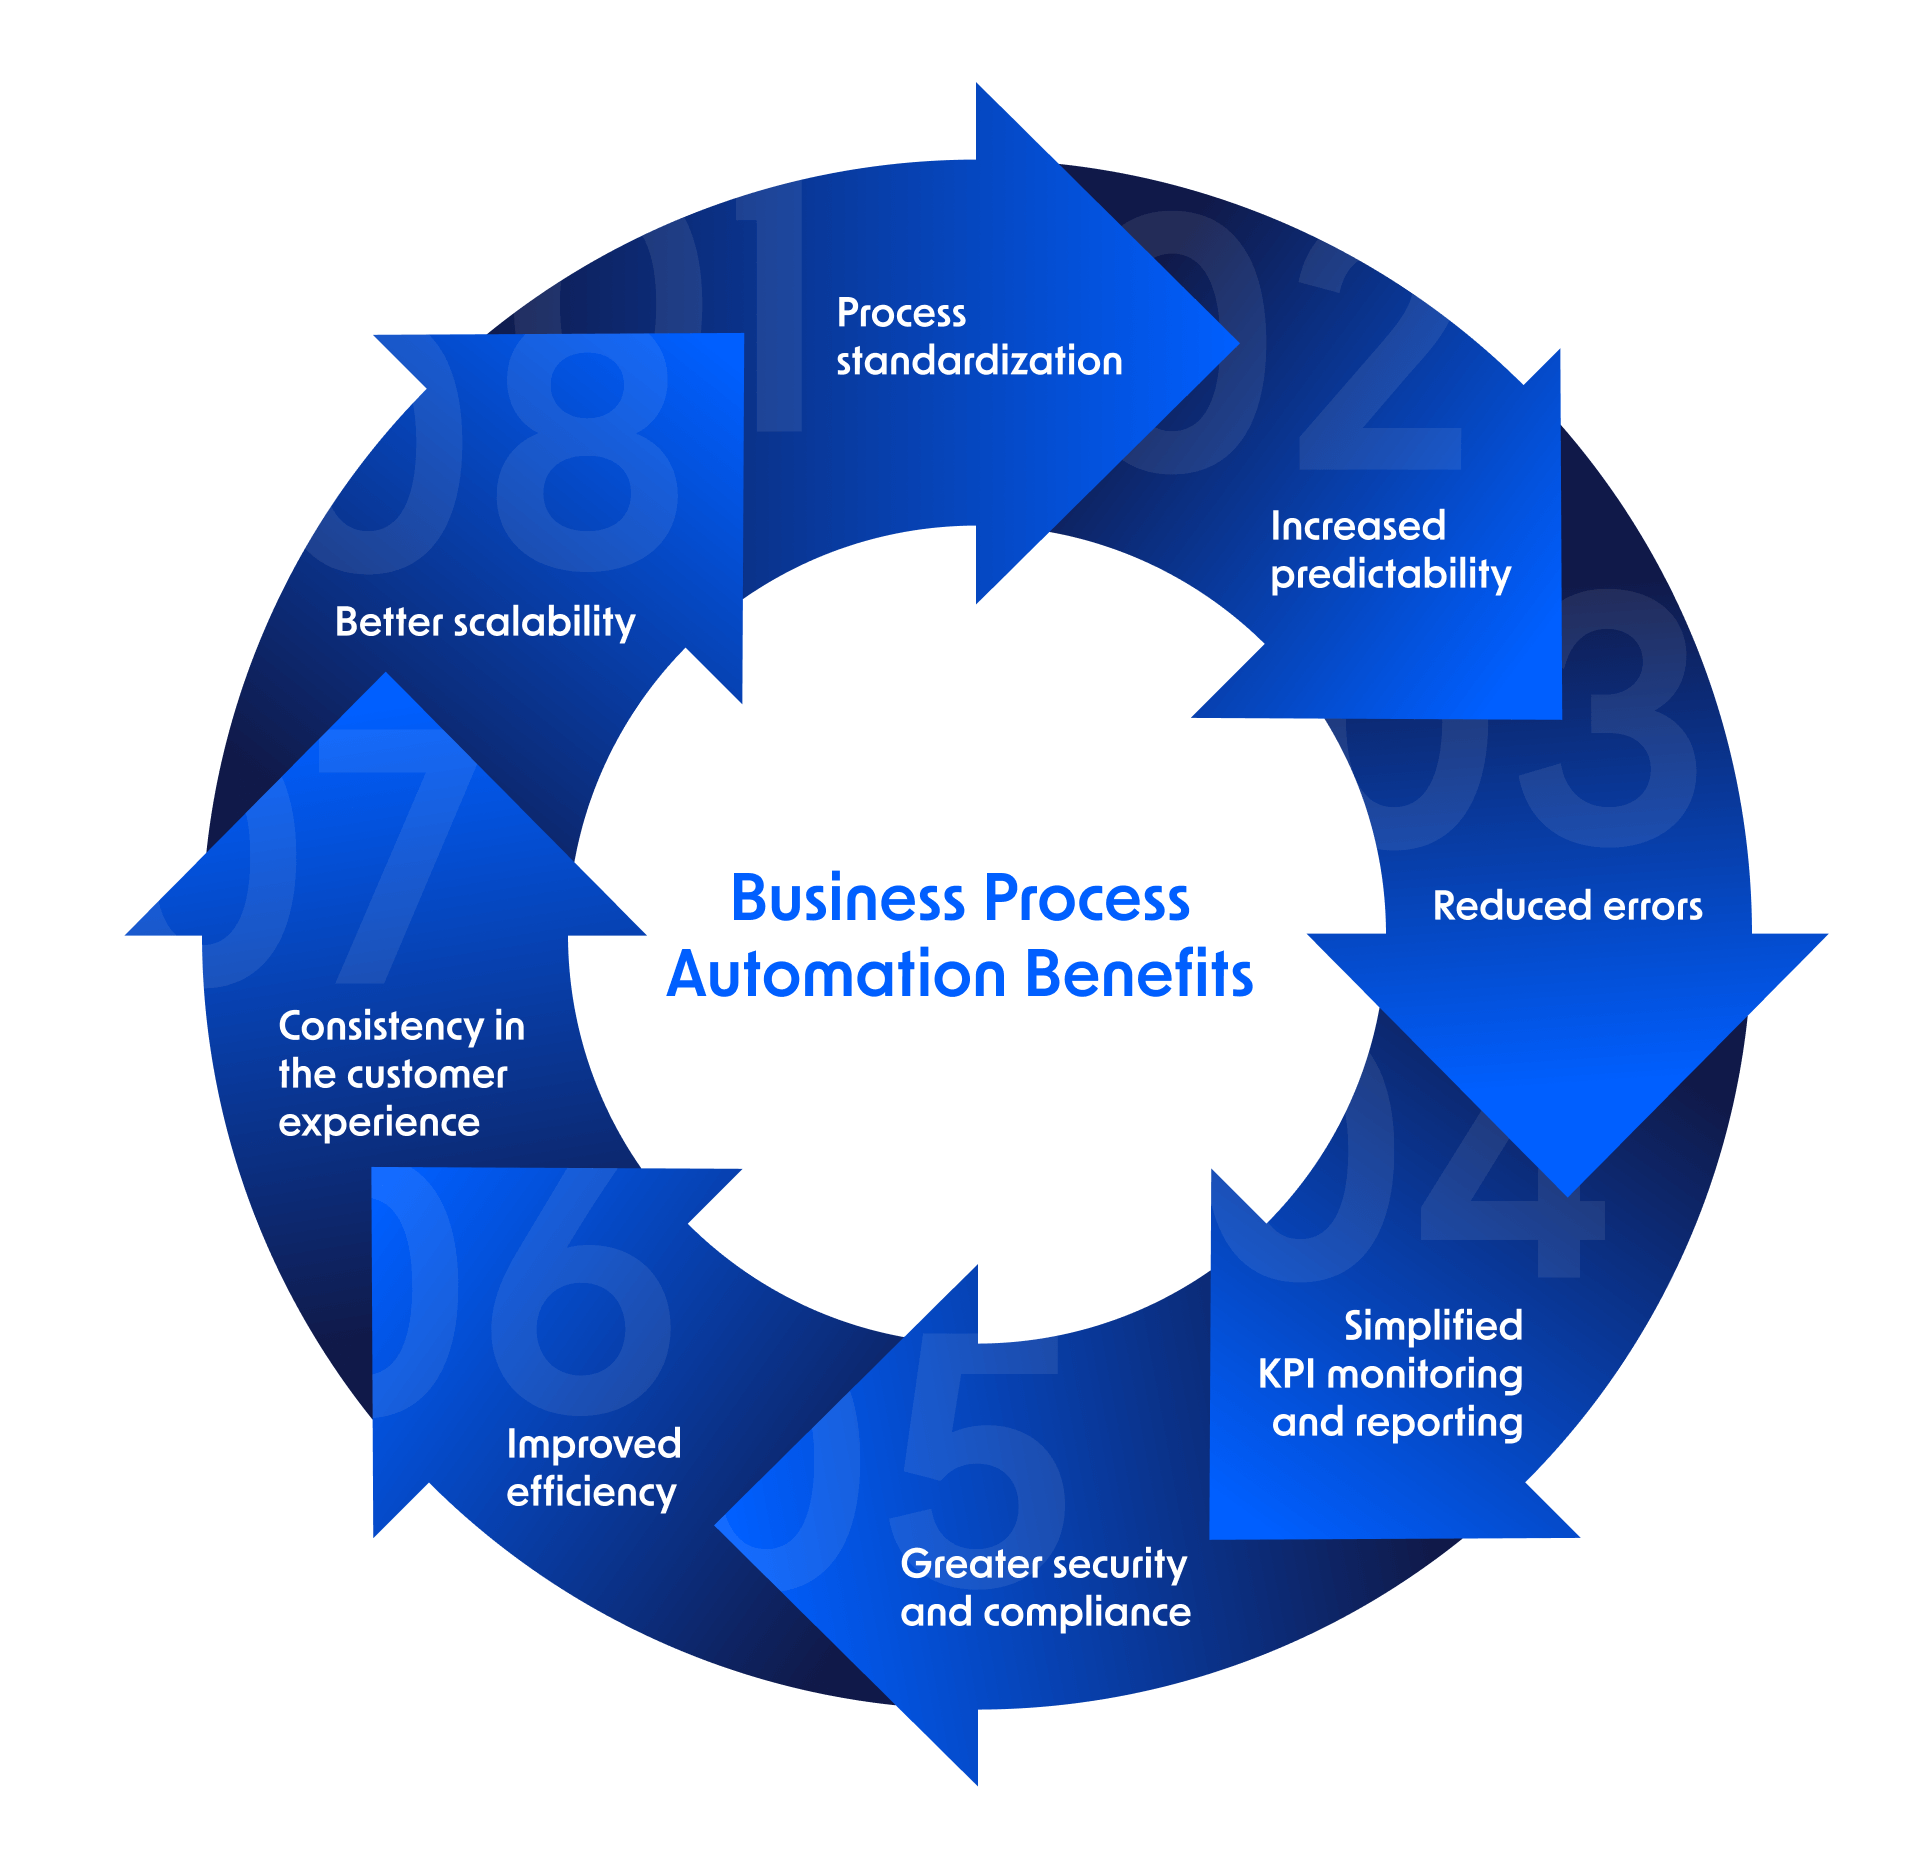
Real Estate Investing for Beginners: 4 Strategies
From rental properties to REITs, four real estate investing strategies accessible to beginners at any budget.
Read More
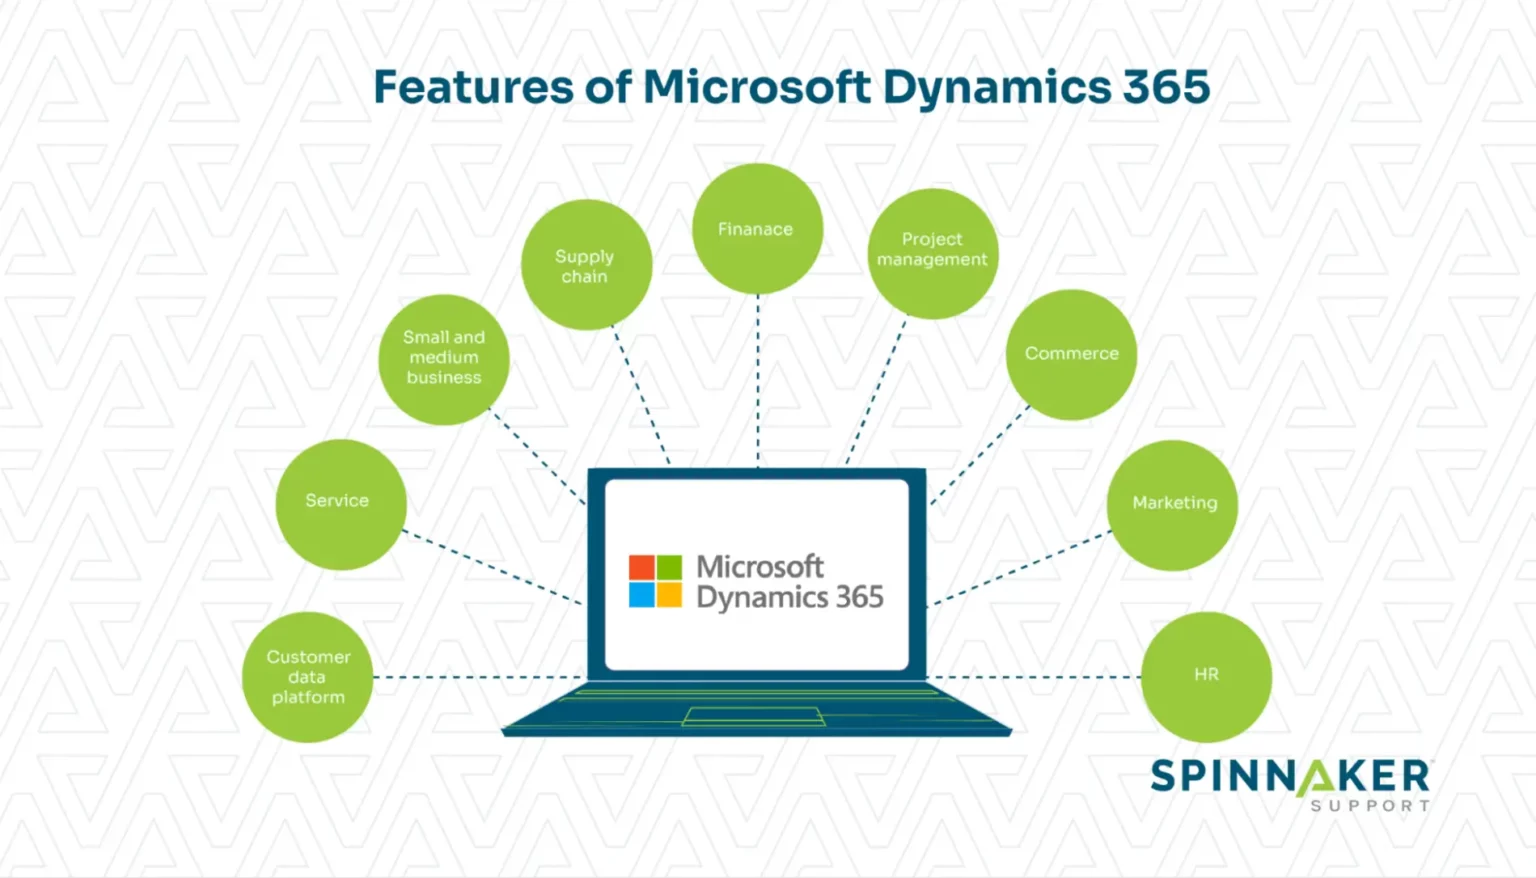
Microsoft Dynamics 365 ERP Benefits
Discover Microsoft Dynamics 365 ERP benefits, features, pricing, and implementation guide. Learn how D365 Finance & Operations transforms business management.
Read More