Understanding Uninsured Motorist Coverage: Why You Need It Even If You Have Full Coverage
What Uninsured Motorist Coverage Actually Does
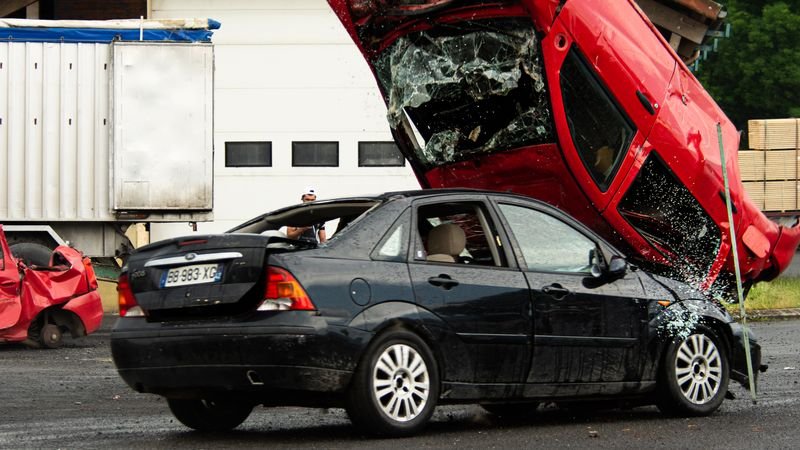
Uninsured motorist coverage, commonly abbreviated as UM or UM/UIM, is a type of car insurance that pays for your injuries and damages when you are hit by a driver who either has no insurance at all or does not have enough insurance to cover your losses. It essentially steps in and acts as if you are filing a claim against the other driver's insurance, except your own insurer pays the bill. This coverage is separate from your collision coverage and your liability coverage, and it serves a very different purpose than either one. While liability coverage pays for damage you cause to others, and collision coverage pays for damage to your own vehicle regardless of fault, uninsured motorist coverage specifically addresses the gap that exists when someone else is at fault but cannot pay for the harm they caused.
The Two Types: Uninsured and Underinsured
Most policies bundle two related coverages together under the UM/UIM label. Uninsured motorist coverage applies when the at fault driver has zero insurance. This includes hit and run accidents where the other driver flees the scene and cannot be identified. In most states, a hit and run is treated the same as an accident with an uninsured driver for coverage purposes, which means your UM policy will pay for your injuries and, in some states, the damage to your vehicle.
Underinsured motorist coverage applies when the at fault driver has insurance, but their policy limits are not high enough to cover your damages. For example, if the other driver carries the state minimum of $25,000 in bodily injury liability and your medical bills total $80,000, their insurance pays the first $25,000 and your underinsured motorist coverage can pay up to your policy limit for the remaining $55,000. Without this coverage, you would need to sue the other driver personally to recover that difference, which is often a futile exercise because drivers who carry minimum coverage rarely have significant personal assets to go after.
Why One in Eight Drivers Is Uninsured
The statistics on uninsured driving make a strong case for carrying UM coverage. Approximately 12.6 percent of drivers nationwide are uninsured, according to the most recent data from the Insurance Research Council. In some states, the percentage is much higher. Mississippi leads the country with an uninsured rate above 29 percent, meaning nearly one in three drivers on Mississippi roads has no insurance. Other states with high uninsured rates include New Mexico, Michigan, Tennessee, and Washington, all of which have rates above 15 percent.
Even in states with relatively low uninsured rates, the risk is not negligible. Virginia and Massachusetts have uninsured rates around 6 percent, but if you drive frequently, you are sharing the road with uninsured drivers every single day. The probability of being involved in an accident with an uninsured driver over a ten year period is significantly higher than the annual statistics suggest because the risk compounds over time. When you add in underinsured drivers, who carry only the bare minimum coverage required by their state, the number of drivers who cannot fully compensate you after a serious accident grows to an estimated 25 to 35 percent in most states.
How Much Uninsured Motorist Coverage You Should Carry
Insurance professionals generally recommend carrying uninsured motorist limits that match your liability limits. If you carry 100/300 liability coverage, meaning $100,000 per person and $300,000 per accident, you should carry the same limits for your UM/UIM coverage. The logic behind this recommendation is straightforward: your liability limits represent your judgment about how much a serious accident can cost. If you believe a bad accident could cost $100,000 per person, then you should also protect yourself to that level when someone else causes the accident.
The cost of UM/UIM coverage is remarkably low relative to the protection it provides. Adding 100/300 uninsured motorist coverage to a policy typically costs between $50 and $150 per year, depending on your state and insurer. Compare that to the potential cost of a serious accident where the at fault driver has no insurance: a single surgery can cost $30,000 to $100,000, a week in the hospital can run $10,000 to $50,000, and ongoing physical therapy or rehabilitation can add thousands more. The math makes this one of the most cost effective coverages you can buy.
State Requirements and Variations
About 20 states require drivers to carry some form of uninsured motorist coverage, though the required minimums vary. Illinois requires 25/50 UM coverage, meaning $25,000 per person and $50,000 per accident. New York requires the same. Other states like Oregon, Connecticut, and New Jersey also mandate UM coverage at various levels. In states that require it, the coverage is automatically included in your policy unless you specifically reject it in writing, and even then, some states make the rejection process intentionally cumbersome to discourage drivers from opting out.
In states where UM coverage is optional, your insurer is still required to offer it to you. If you declined it in the past because you were trying to save money on your premium, it is worth reconsidering that decision. The cost difference between having UM coverage and not having it is usually less than $15 per month, and the financial exposure you face without it is enormous. A single accident with an uninsured driver could leave you with medical bills, lost wages, and pain and suffering that you have no practical way to recover without this coverage.
How Filing a UM Claim Works
Filing an uninsured motorist claim is different from a standard third party claim in several important ways. When you file a UM claim, you are technically filing a first party claim with your own insurer, but the process operates under the rules of third party liability. This means you need to establish that the other driver was at fault and prove the extent of your damages, just as you would if you were filing a claim against the other driver's insurance. Your insurer will investigate the accident, review medical records, and may dispute the amount of your damages even though they are your own insurance company.
One important thing to know is that UM claims do not affect your insurance rates in most states. Because the accident was not your fault, your insurer cannot raise your premium for filing a UM claim. However, some states allow insurers to consider the number of UM claims you have filed over a period of time as a rating factor, so it is worth checking your state's rules. The claims process itself can take anywhere from a few weeks to several months depending on the severity of your injuries and whether there is a dispute about the value of your claim. If you and your insurer cannot agree on a fair settlement, most UM policies include an arbitration clause that allows you to resolve the dispute through binding arbitration rather than going to court.
Stacking: Multiplying Your Coverage Limits
Some states allow a practice called stacking, which lets you multiply your UM coverage limits by the number of vehicles on your policy. If you have two cars insured with 100/300 UM coverage and your state permits stacking, your effective UM coverage doubles to 200/600. This can make a significant difference in a serious accident. States that allow stacking include Pennsylvania, Florida, Virginia, and several others. Your insurer may charge a small additional premium for stacked coverage, but the cost per dollar of additional coverage is typically very low.
Even in states that allow stacking, some policies include anti stacking provisions that limit your coverage to the single vehicle limit. If stacking is important to you, make sure you read your policy carefully or ask your agent specifically whether your policy permits it. Switching to an insurer that offers stacked UM coverage can effectively double your protection for only a modest increase in premium, making it one of the most efficient ways to increase your overall coverage level.
Insurance Bad Faith: When Insurers Break the Law
Insurers that delay, deny, or underpay claims can be sued for bad faith. Learn what that means and what you can recover.
Read More
SAP ERP Implementation Guide
Complete SAP ERP implementation guide covering S/4HANA migration, costs, timeline, best practices, and success strategies for enterprise digital transfor
Read More
Best Crypto Exchanges 2024: Full Comparison
Coinbase, Kraken, Binance, Gemini, compared on fees, security, and features so you pick the right one.
Read More