How Car Modifications Affect Your Insurance Rates: What You Need to Know Before Upgrading
Why Insurance Companies Care About Your Modifications
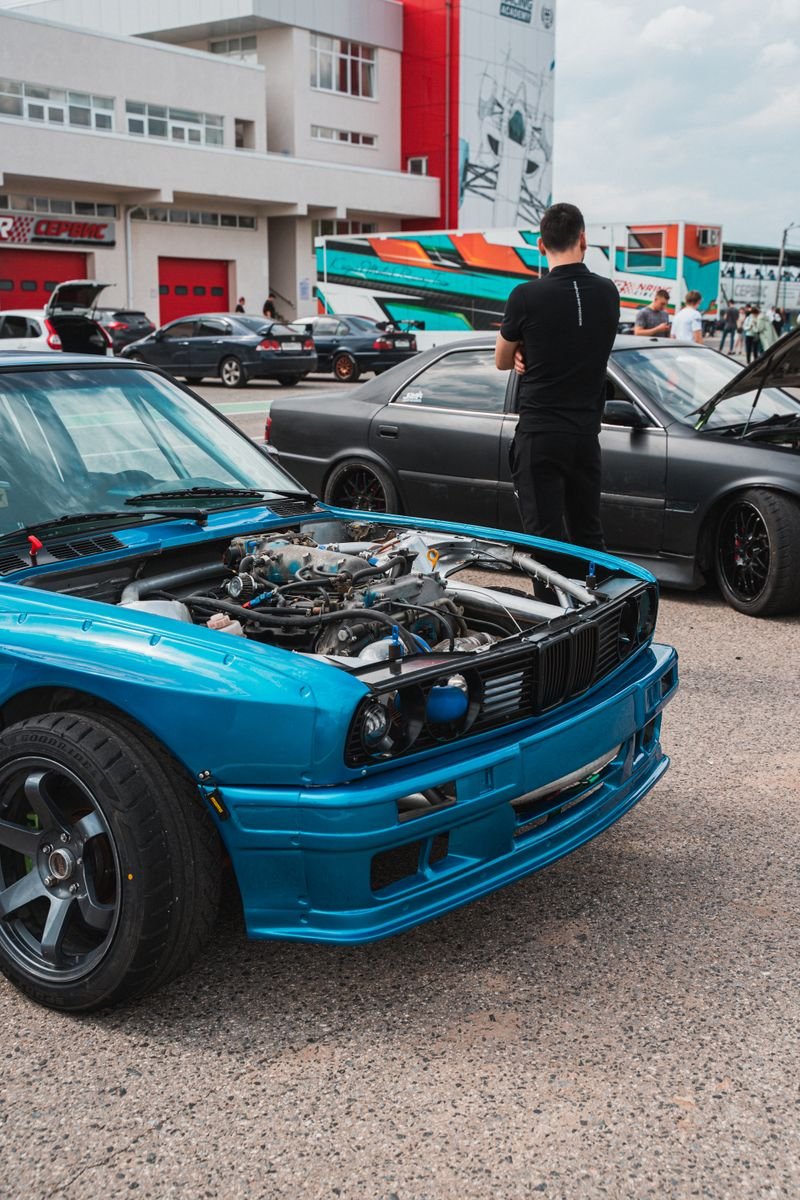
When you modify your car, you are changing the risk profile that your insurance company originally priced your policy around. Every modification has the potential to affect the value of your vehicle, its performance characteristics, the cost to repair it after an accident, and even the likelihood that it will be stolen. Insurance companies price policies based on actuarial data, and when you change the vehicle from its factory specifications, the original data may no longer apply. A car that has been modified with a turbo kit and performance exhaust behaves differently on the road than the stock version, and a vehicle with expensive aftermarket wheels is a more attractive target for thieves. These are the kinds of risk factors that insurers evaluate when adjusting your premium for modifications.
Performance Modifications That Raise Your Rates
Any modification that increases your vehicle's horsepower, torque, or top speed is almost certain to raise your insurance premium. This includes engine swaps, turbocharger and supercharger installations, performance exhaust systems, cold air intakes, ECU tuning, and nitrous oxide systems. Insurers view these modifications as increasing the likelihood of accidents because higher performance vehicles are driven more aggressively on average. The data supports this view: claims frequency for vehicles with performance modifications is measurably higher than for stock vehicles, and the severity of those claims tends to be higher as well because accidents at higher speeds cause more damage.
Suspension modifications that lower your vehicle below factory specifications can also raise your rates. While lowering a car can improve handling in controlled conditions, insurers associate lowered vehicles with aggressive driving and higher claims frequency. Conversely, lifting a truck or SUV significantly above factory height can raise rates because lifted vehicles have a higher center of gravity and are more prone to rollover accidents. The cost increase for performance modifications typically ranges from 10 to 25 percent of your base premium, though extreme modifications like engine swaps can push that number higher.
Cosmetic Modifications and Their Surprising Impact
Not all cosmetic modifications affect your insurance, but several common ones do. Aftermarket wheels and tires are a good example. If you replace your factory wheels with expensive forged wheels that cost $3,000 per set, you have increased the replacement cost of your vehicle in the event of a covered loss. Your standard policy may not cover the full value of those wheels unless you have declared them to your insurer and added them to your policy. Custom paint jobs, vinyl wraps, and specialty body kits also increase the replacement value of your vehicle and should be reported to your insurer.
Window tinting is a modification that some drivers do not think to report, but it can affect your insurance in certain states. Heavy tinting that exceeds legal limits in your state is technically a violation, and if you are involved in an accident while driving a vehicle with illegal tint, your insurer could argue that the tint contributed to the accident by limiting your visibility. Even legal tinting can be a factor if it is dark enough to obscure the interior of the vehicle, because vehicles with heavily tinted windows are statistically more likely to be involved in theft related claims.
Modifications That Could Lower Your Premium
While most modifications increase your insurance costs, some can actually lower your premium. Anti theft devices like alarm systems, GPS tracking systems, kill switches, and steering wheel locks reduce the risk of theft, and many insurers offer discounts ranging from 5 to 15 percent for vehicles equipped with approved anti theft systems. Dashcams are another modification gaining traction with insurers: some companies offer discounts for drivers who install front and rear dashcams because the footage can help resolve liability disputes and reduce fraudulent claims.
Safety modifications can also help. Upgrading your headlights to brighter, more effective units, adding backup cameras to older vehicles, or installing blind spot monitoring systems can qualify you for safety equipment discounts with some insurers. However, these discounts are not universal, and you should check with your insurer before assuming a safety modification will lower your rate. The discount for safety equipment is typically smaller than the surcharge for performance equipment, so you cannot offset a turbo kit with a dashcam and expect your premium to stay the same.
The Importance of Declaring Modifications to Your Insurer
Many drivers skip telling their insurance company about modifications because they do not want their rates to go up. This is a risky strategy that can backfire badly when you need to file a claim. If your insurer discovers undeclared modifications during the claims process, they can reduce your payout to reflect the stock value of the vehicle rather than the modified value. In more serious cases, they can deny your claim entirely on the grounds of material misrepresentation, which means they argue that you provided false information about the vehicle and that they would have priced or underwritten the policy differently if they had known about the modifications.
The consequences go beyond a single claim. If your insurer cancels your policy due to undisclosed modifications, you will have a cancellation on your insurance history, which makes it significantly more expensive to get coverage from another company. Insurers share information through databases, and a cancellation for misrepresentation is a red flag that will follow you for years. The small amount you save by not reporting modifications is rarely worth the risk of a denied claim or policy cancellation.
Specialty Insurance for Heavily Modified Vehicles
If your vehicle has extensive modifications, a standard auto insurance policy may not be the best fit. Several companies specialize in insuring modified, custom, and collector vehicles, and their policies are designed to cover the full value of your modifications without the restrictions and surcharges that standard insurers impose. Companies like Hagerty, Grundy, and American Collectors offer agreed value policies that set the value of your vehicle upfront based on its modified condition. This means that in the event of a total loss, you receive the full agreed upon value rather than whatever a standard insurer's adjuster decides your modified vehicle is worth.
Specialty policies do come with some restrictions. Many require that the modified vehicle not be your daily driver, or they limit the number of miles you can drive per year. Some require that the vehicle be stored in a garage when not in use. If your modified car is your only vehicle and you drive it daily, a specialty policy may not work for you, but it is worth getting a quote to compare against what standard insurers are charging with modification surcharges included. In some cases, a specialty policy with mileage restrictions is actually cheaper than a standard policy with modification surcharges, especially for vehicles with $10,000 or more in aftermarket parts.
Tips for Keeping Insurance Costs Manageable on a Modified Vehicle
If you plan to modify your vehicle and want to keep insurance costs reasonable, start by talking to your insurer before you begin the work. Ask them specifically which modifications will trigger a rate increase and by how much. This lets you factor the ongoing insurance cost into your modification budget rather than being surprised at renewal time. You should also get quotes from multiple insurers, because companies vary widely in how they treat modifications. One company might charge a 20 percent surcharge for the same modification that another company charges 5 percent for.
Document everything you install on your vehicle. Keep receipts, take photographs before and after each modification, and maintain a detailed list of all aftermarket parts with their values. This documentation is essential if you ever need to file a claim, because it establishes the value of your modifications and makes it much harder for an insurer to undervalue your vehicle. Finally, consider joining a car club or enthusiast organization, because some insurers offer group discounts to members of recognized automotive clubs. These discounts can partially offset the surcharges associated with modifications and make the overall cost of insuring your modified vehicle more manageable.
Tenant Rights You Should Know
Protect yourself from unfair landlords by understanding the rights the law gives you.
Read More
Slip and Fall Claims: What You Need to Prove
Property owners can be held liable for unsafe conditions. Here's what it takes to win a slip and fall claim.
Read More
Best Coding Bootcamps 2024: Programs Compared
Bootcamps promise developer jobs in 6 months. Here's which programs deliver, and what employers actually think.
Read More